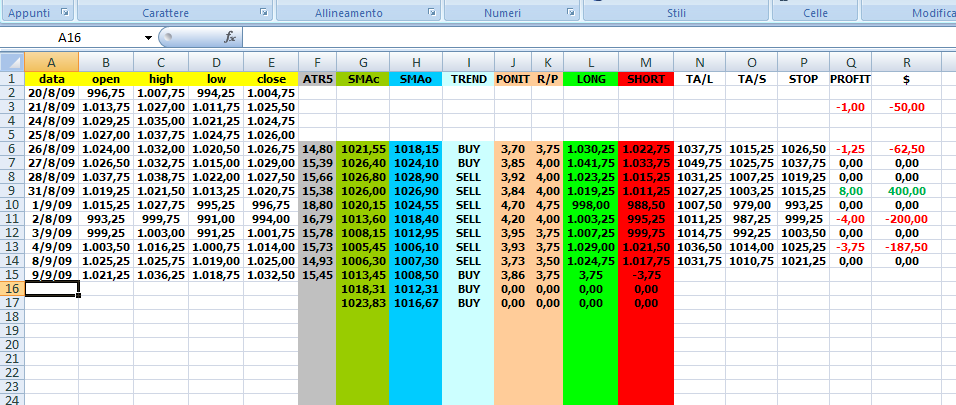
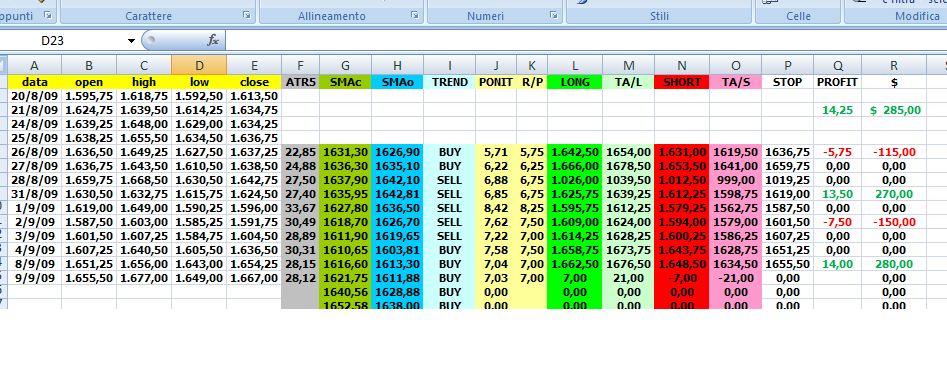
Wanted to offer the following in the hope that others might review with a constructive eye and, perhaps, conduct additonal backtesting. My technical abilities are limited, so I backtest manually.
The results for the 28 trading days between Apr 2 - May 12 on NQ June show 19 trades. 13 W 164 points 5L 29.75 points 1 BE. Gross of 134.25 points - $2685 before commission
Methodology
Chart set up: On a day session chart plot the 5 period average true range. Also plot a 5 period simple moving average of both the close and the open. Longs are taken only when the 5 period SMA of the close is above the 5 period SMA of the open. Shorts only when below.
Entries and Exits: If taking longs, add 50% of yesterday's ATR to today's open. This is the entry. Exits are either - a stop order at today's open, limit order at 50% of yesterday's ATR added to today's open, or MOC. For shorts simply reverse.
Having a target that is twice the stop really helped when I manually tested this for the same period as above on the 10 yr note (ZN June). 18 trades were taken. 8 W 83.5 points 10 L 47.5 points Gross of 36.5 points - $1140.62 before commission.
Thanks in advance for your constructive ideas for improvement and any additional backtesting you might undertake.
edit - 25% atr changed to 50%
ST
stifland
Rep: 0
Posts: 15
This seems very interesting. So to be clear. On ES. Close > Open MA so look only Long. Fridat atr , I show was 23.95. SO entry would be 6 points from open and target 12 points from open? So this is a 1 to 1 RR. 6 point target and 6 point stop in this case, correct?
Thanks
Thanks
ST
stifland
Rep: 0
Posts: 15
my bad, I C you add the 50%, therefore a 12 point target and 6 point stop, cool.
PA
PaulR
Rep: 130
Posts: 119
Actually for Friday I have a daily 5 per ATR of 22.89 so price would have to move up 5.75 from open today for entry and the target would be 11.50 from open with stop back at open. I'm sure the difference is probably due to variations in our data feed. Mine is IB.
BUt you've got the core of this approach right. Hopefully it'll get back on the winning side of things after a few bad days. :-)
BUt you've got the core of this approach right. Hopefully it'll get back on the winning side of things after a few bad days. :-)
quote:
Originally posted by stifland
This seems very interesting. So to be clear. On ES. Close > Open MA so look only Long. Fridat atr , I show was 23.95. SO entry would be 6 points from open and target 12 points from open? So this is a 1 to 1 RR. 6 point target and 6 point stop in this case, correct?
Thanks
PA
PaulR
Rep: 130
Posts: 119
See previous post for today's ES. NQ is long @ 8.75 above open. Target +17.50. ZN went short @ 116-115 this morning. Stop @ 116-230. Target 115-205. (sorry this was late)
PA
PaulR
Rep: 130
Posts: 119
quote:
Originally posted by stifland
right, i have open 932. entry of 938. high 37.25 so far.........
We're close. I have open of 32.50. +5.75 gives entry of 38.35.
PA
PaulR
Rep: 130
Posts: 119
quote:
Originally posted by PaulR
quote:
Originally posted by stifland
right, i have open 932. entry of 938. high 37.25 so far.........
We're close. I have open of 32.50. +5.75 gives entry of 38.35.
That's 38.25. And ZN is the Sep contract.
PA
PaulR
Rep: 130
Posts: 119
That's more like it! All 3 triggered & were green. ES went long and exited MOC @ 4PM for +4.25/$212.50 per contract. NQ went long and delivered +17.50/$350 per contract. ZN went short and tallied +23/32's $718.75 a contract. Total $1281.50 on 1 contract each. A nice start to June.
ST
stifland
Rep: 0
Posts: 15
Yes, my 3:00 close shows 40.25 which woyld be +2.25, but I doubt I would have waited that long. I guess my question is that we gave up about 7 points from the highs. So just wondering on how a phased out exit strategy may work. I'll keep watching. Looks great. I show long again tomorrow with ATR of 27.30.
Cheers,
billy
Will be at DR. so won't be trading it :(
Cheers,
billy
Will be at DR. so won't be trading it :(