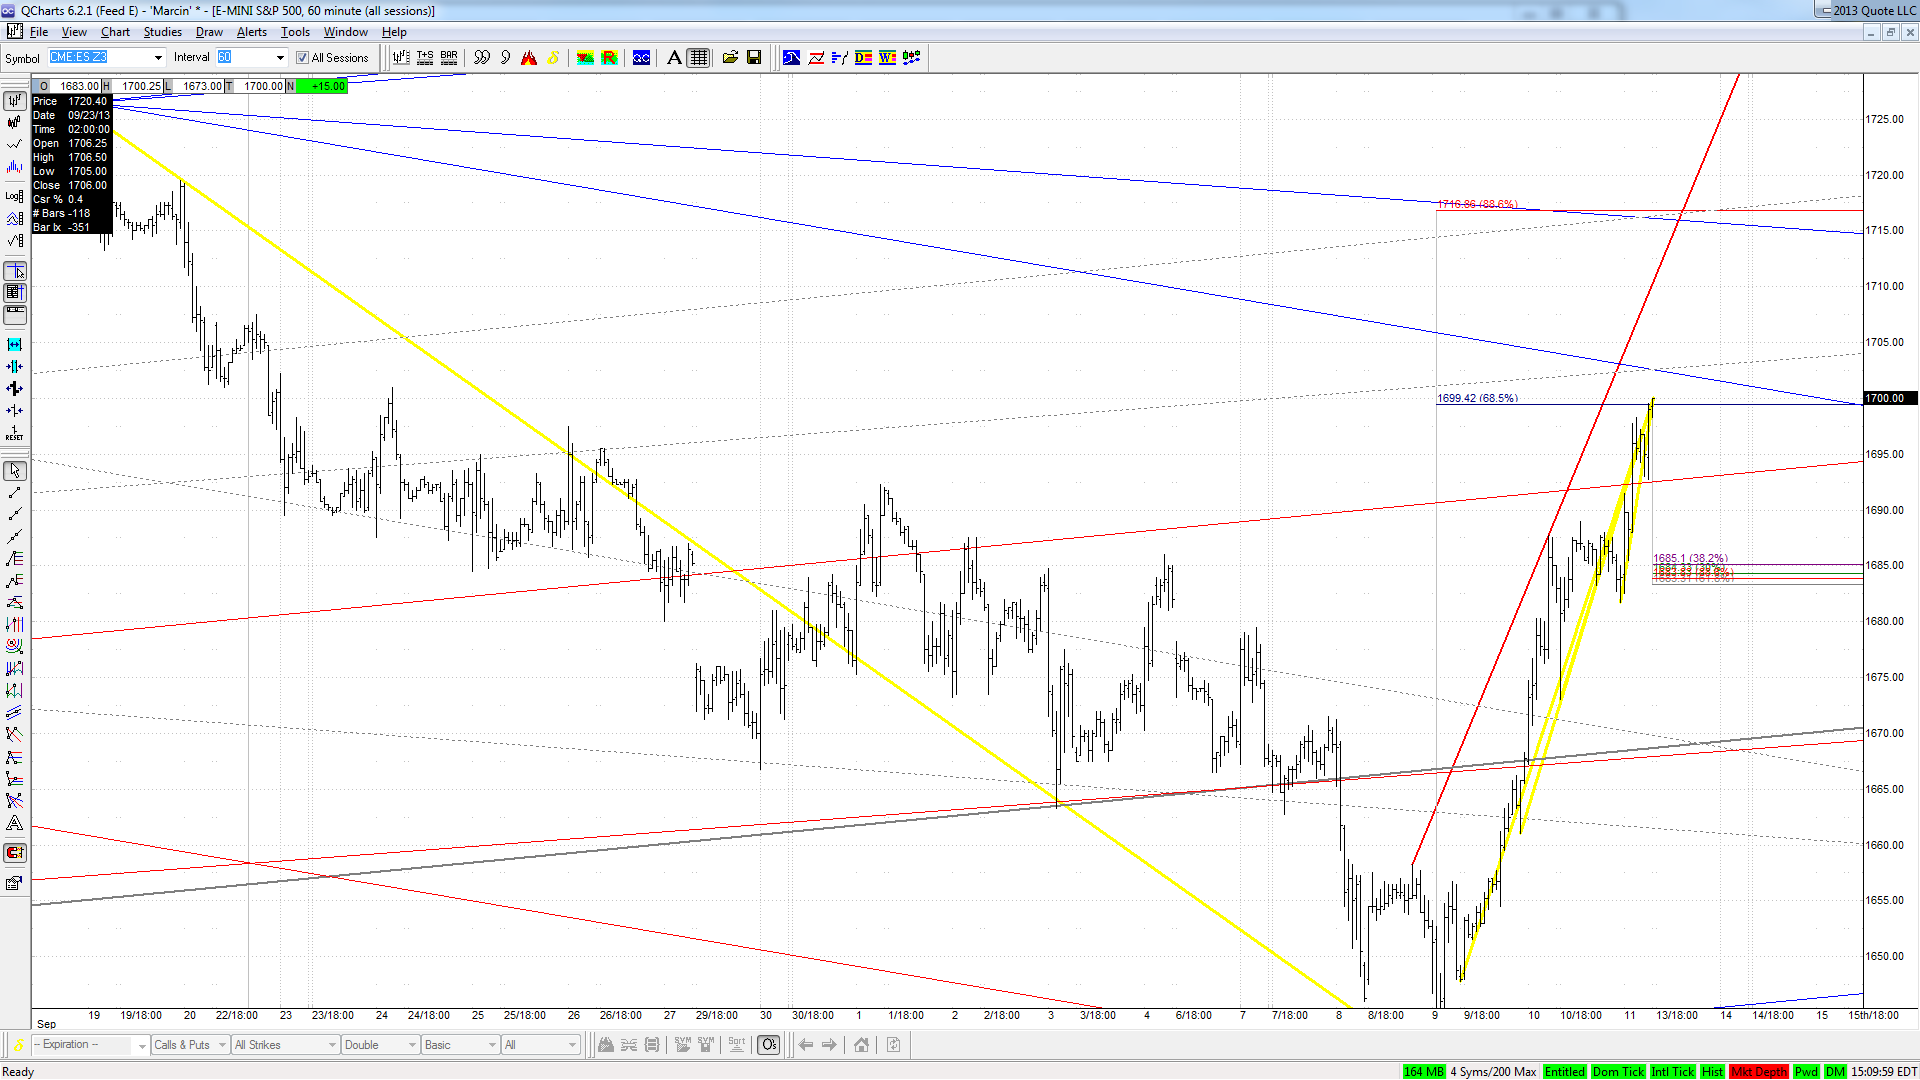
Some areas for ES. If a fifteen point drop anticipated by ZH is going to happen, it will fall into a nice grouping.
http://www.zerohedge.com/news/2013-10-13/early-fx-indications-eurjpy-slide-implies-15-point-futures-drop-open
JI
jimkane
Rep: 3,058
Posts: 33,089
Like I said, the plan for awhile now, just buy one minute before the open, give it some room, hold on, take 12-14, or maybe a lot more, out. No skill needed.
JI
jimkane
Rep: 3,058
Posts: 33,089
Can't wait until tomorrow. I'm going to program my system to buy at 6:29 AM (Pacific time). Then I'll sleep in, get up at say 8:00 AM and see if it's time to take my 12-14 points (or occasionally 20-30), quit for the day, and go have fun. That should be, what, let's say one day stops me out one day is say 25 (assume it alternates between 20 and 30), three 13's (average of 12 and 14) and say 6 on the stop. So, I'll net 58 points per week. If I use a conservative $10,000 for margin, I net $2,900 per contract per week. So, that would be $145,000 per year, or a 1450% return, uncompounded (assuming 50 weeks, I'd want some vacation), per contract.
If I 'compounded' each week (one would realistically compound daily), that would be 3,384,238% per year (assuming 50 weeks). That's not too bad. Now, let's say I compounded daily that would be 132,256,470% per year. The last digit there my calculator didn't have room for, so I made it a zero. This also assumes, as did the weekly calculation, that every day was the same return, the average return. So, the calculations would be approximations, of course. Hence, I think the best plan is to compound daily, increasing my contracts as needed. I wonder how many contracts I'd be trading after a year?
What I like about this plan is it takes no skill. And the market, as we all know, is dying to provide this kind of money to the beginner, the amateur, the poor and struggling. I think we should teach this to everyone, so they can all make over a hundred million percent a year. But, with Old Yeller having our back, and bear markets a thing of the past (they finally managed to smooth out the business cycle and reach a permanent plateau of prosperity), this should be no problem. Long live the King!
P.S. If anyone takes this as a serious post I'm going to scream.
If I 'compounded' each week (one would realistically compound daily), that would be 3,384,238% per year (assuming 50 weeks). That's not too bad. Now, let's say I compounded daily that would be 132,256,470% per year. The last digit there my calculator didn't have room for, so I made it a zero. This also assumes, as did the weekly calculation, that every day was the same return, the average return. So, the calculations would be approximations, of course. Hence, I think the best plan is to compound daily, increasing my contracts as needed. I wonder how many contracts I'd be trading after a year?
What I like about this plan is it takes no skill. And the market, as we all know, is dying to provide this kind of money to the beginner, the amateur, the poor and struggling. I think we should teach this to everyone, so they can all make over a hundred million percent a year. But, with Old Yeller having our back, and bear markets a thing of the past (they finally managed to smooth out the business cycle and reach a permanent plateau of prosperity), this should be no problem. Long live the King!
P.S. If anyone takes this as a serious post I'm going to scream.
JI
jimkane
Rep: 3,058
Posts: 33,089
Can you tell how bored a 5.50 point range for about four hours makes me?
JI
jimkane
Rep: 3,058
Posts: 33,089
This really states one of my main frustrations. Why I am posting it is because of how he says things will look fine until the critical point, then you're toast, no warning. I believe that can, many times, be exactly true. We will just wake up one day to the news and be shocked. Until then, happy days are here again. Like I said many times, we won't ever have another bear market again. This will go up until the world as we know it ends, and that will happen in one quick shot. One event, and it's all over. That's my highest probability scenario.
http://market-ticker.org/akcs-www?post=225124
JI
jimkane
Rep: 3,058
Posts: 33,089
Yeah, Marcin, that's all it should do. Then up to new all-time highs.
JI
jimkane
Rep: 3,058
Posts: 33,089
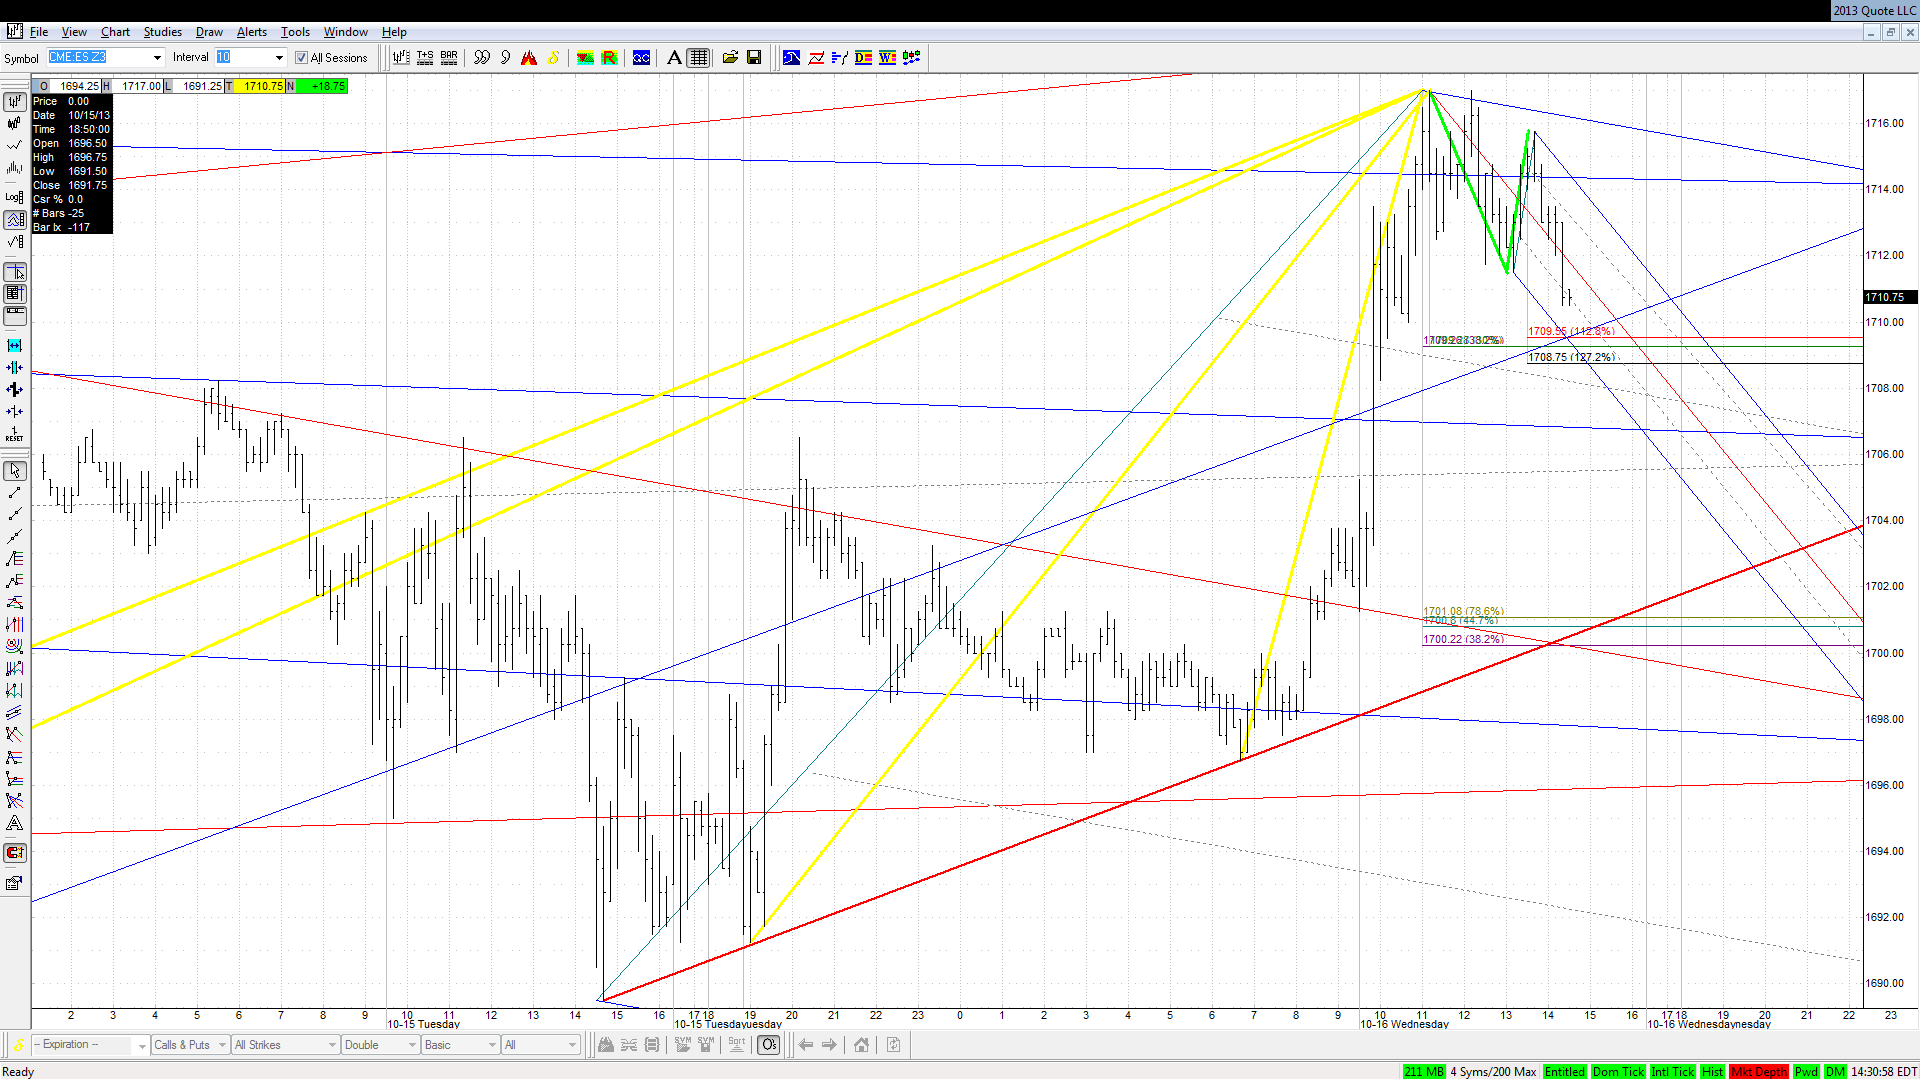
Okay, just a tiny vibe I'm getting here that this bearish EXP ABCD is going to produce a reaction. Interesting.
JI
jimkane
Rep: 3,058
Posts: 33,089
Zzzzzzzzzzzzzzzzzzzzzzz. Just waiting on the new HOD. This is set up nicely for a rise all night. Wouldn't they want to bring it in for better prices, though, then goose it straight up off the open? Decisions, decisions. All I can say is, I think traders should be thanking their lucky stars for all this 'easy money'.
JI
jimkane
Rep: 3,058
Posts: 33,089
So, while people are busy fighting the long side and looking for the S&P to reverse in here the same exact pattern that's happened time and time and time again has unfolded. Russell and MidCaps at new all-time highs, NDX and Naz comp at new highs for the entire 'bull', with the NDX very, very strong. Nuttin' but up.
JI
jimkane
Rep: 3,058
Posts: 33,089
So, they keep saying there is no inflation, and we need more inflation. Let's see. I got my prescription the other day. It was up. 265% My better half just called me from the grocery, my almonds are up from last time. 20%. I looked at my tax software for this year. It was up. 33.33%. Recall that link I posted for health plans and all those triple digit increases. Nope, all that doesn't sound like any inflation to me. I agree, we need lots more.
BTW, let's quickly talk about the CPI. Now, for me, my medical insurance is almost 40% of my total expenditures. So, for me, I'd like the CPI weighted so medical insurance is figured at about that level, say 40%. Look at what others pay. And to do it right, you can't look at all those who pay little getting it from work, and figure that percentage. If your employer is paying for it, it's the same as if you are. In theory, the employer could just pay you more and not include the insurance. It's the same with FICA. I'm self-employed, so I pay 15.3%. Workers pay 7.15%, but their employer pays the other 7.15%. If they didn't, they could pay you 7.15% more. So, you pay it all, regardless. I think 99.99%, literally, of people are simply unable to comprehend that fact no matter how many times it is explained to them. It's just a limitation of the human mind (and poor education), and it a big part of why we are in the mess we are in.
Anyway, I think the CPI should weight medical insurance between 20% and 40%, but more towards the latter. And since this is one of the fastest increasing expenses, it is very important that it be weighed accurately, to insure accuracy in the CPI. The current weighting? 0.6%. Yes, 0.6%. Well, that's a nice way to keep those old inflation figures down. The Chinese recently did the same thing with housing data. They tweaked the weighting of houses, and the weighting of rural/city data, and so on. Presto, no inflation in China. EZ-PZ. Yep, there's no inflation.

